A short clause with real consequences
Most homeowners, condo and commercial property forms sold in Delaware include a paragraph headed “Appraisal.” In plain terms it says: if you and the insurer can’t agree on the amount of loss, either side can demand appraisal in writing; each side picks a competent and impartial appraiser; the two appraisers pick an umpire; and a written agreement signed by any two of the three sets the amount. That signature rule is why the person you appoint matters. An appraisal clause appraiser in Delaware is not a negotiator who can be ignored — their work becomes part of a binding number.
What we handle as your appointed appraiser
- Policy and demand review. We read the exact appraisal wording, any endorsements and the demand letter, and flag response windows (many forms use 20 days to name an appraiser).
- Our own inspection. We measure and photograph the property ourselves. We do not start by editing the carrier’s estimate.
- A line-item valuation. Built in industry estimating software with current pricing for your part of Delaware — a Wilmington rowhome and a Bethany Beach cottage don’t cost the same to repair.
- Working sessions with the other appraiser. Most disagreements shrink here, line by line, with photos and measurements on the table.
- Umpire selection and presentation. If items stay open, we help choose a qualified umpire and present the remaining differences clearly.
- Award review. We check that the award form separates replacement cost, actual cash value and any categories the policy treats differently before anyone signs.
Where appraisal tends to work
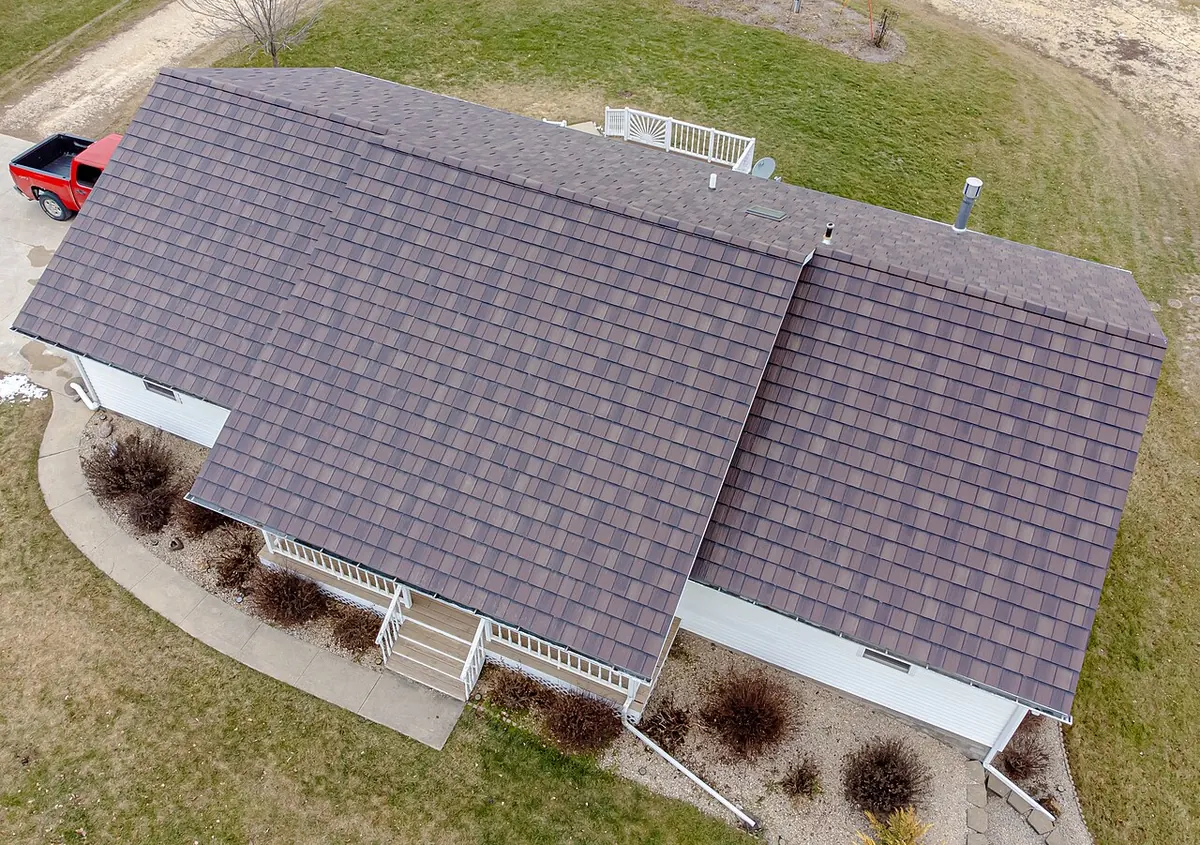
The clause works best on scope and price disputes: how many roof slopes were damaged by wind off the Delaware Bay, whether hardwood can be matched after a pipe burst, what drywall and paint really cost in Kent County this season. It is a weaker tool when the real disagreement is about an exclusion, long-term wear, or whether flood water (not covered by most homeowners forms) caused the damage.
Impartial, but prepared
Many policies require each appraiser to be impartial. We take that seriously: we price what the evidence supports, disclose prior relationships with the other appraiser or umpire, and never take a contingency stake in the repair contract. That credibility is what moves an umpire.
Frequently asked questions
Can my roofer be my appraiser?
Usually that’s a bad idea. Policies commonly require a competent and impartial appraiser, and a contractor who stands to win the repair job may be challenged as interested, which can put the award at risk.
What if the insurer is the one who demanded appraisal?
The process is the same. You still name your own appraiser within the response window the policy sets, and you are not required to use anyone the carrier suggests.
How long does Delaware appraisal usually take?
Straightforward residential panels often wrap up within six to twelve weeks of both appraisers being named. Commercial losses, contents-heavy claims and umpire hearings can take longer.
Related services
Homeowners Claim Appraisal
Houses, twins, rowhomes and condo units where the adjuster’s estimate skips real repair costs.Learn more
Commercial, Condo & HOA Appraisal
Offices, retail, warehouses, multifamily, churches and associations with large or complex losses.Learn more