Why the first estimate comes in short
After a regional storm, adjusters may handle dozens of Delaware files in a week, some flown in from other states. Speed produces the same misses again and again. When we do homeowners insurance appraisal in Delaware, these are the items we see most:
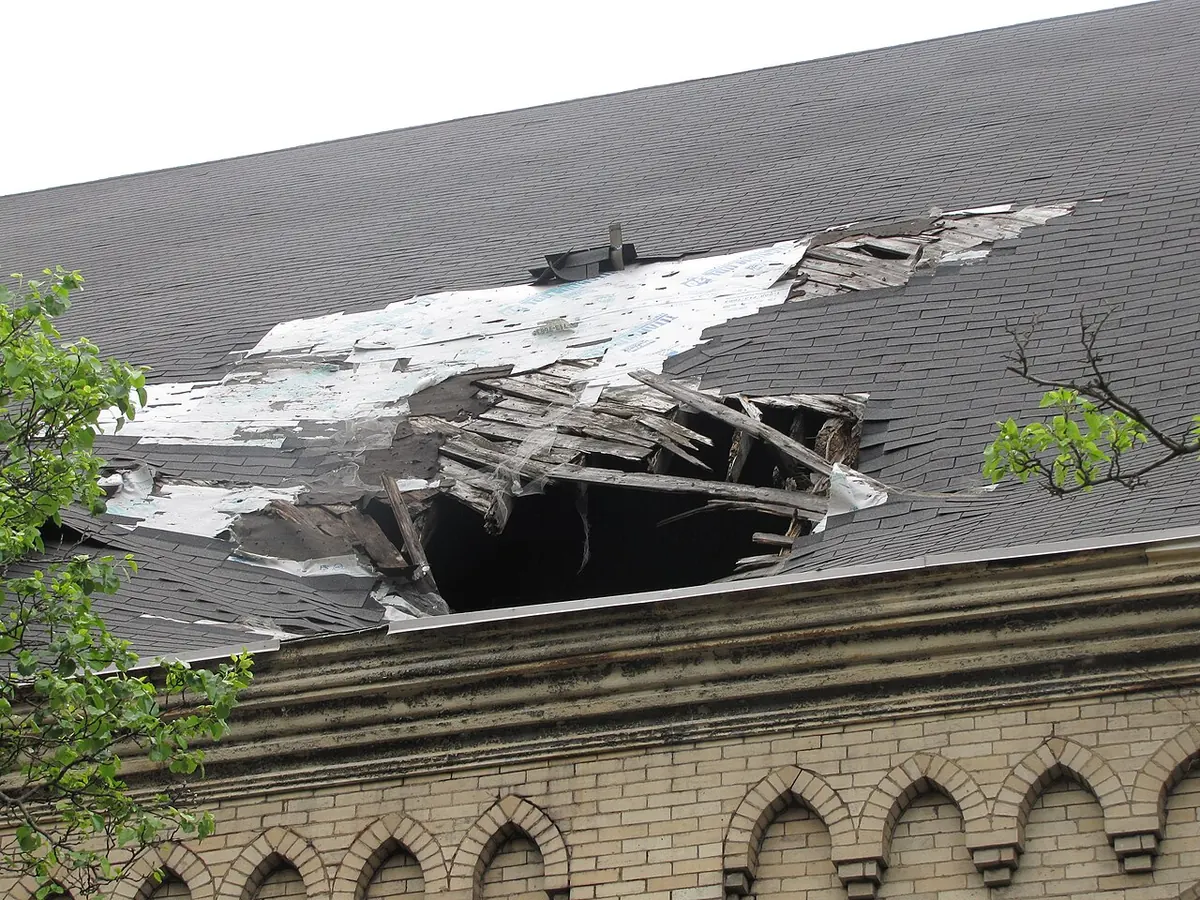
- Repair-only roof approvals on shingles that are discontinued, brittle or impossible to match in color and exposure.
- “Spot paint” interiors where the ceiling or wall finish runs continuously into the next room and can’t be blended.
- Building-code items local permit offices require once work begins — drip edge, underlayment details, smoke and CO detectors, permit fees — often limited by the policy’s ordinance-or-law coverage.
- Trade minimums and setup left off small line items, as if an electrician or plumber drives out for free.
- Other structures — detached garages, fences, sheds, outdoor showers at beach homes — that were never inspected.
- Additional living expense cut off while repairs are still underway.
Our process for a house claim
- We read your declarations page and policy form and confirm which coverages are in play.
- We inspect every affected room, elevation and roof slope and take our own measurements.
- We write a room-by-room estimate with current local pricing.
- We compare it to the carrier’s estimate and give you a plain-English list of every difference and why it exists.
- If you choose appraisal, we serve as your appraiser and carry that work through to an award.
Older homes need extra care
Delaware has a lot of housing built before 1960: rowhomes in Wilmington’s Little Italy and Trolley Square, brick and frame homes around Dover’s historic Green, farmhouses in Sussex County. Plaster walls, old-growth trim and slate or cedar roofs cost more to repair properly than a template estimate assumes. We document those materials so their cost isn’t treated as an upgrade.
Condo unit owners
If you own a unit, your HO-6 policy and the association’s master policy split the building between them. We start by reading the declaration and bylaws so we value only what your policy is responsible for — and nothing falls through the gap between the two.
Frequently asked questions
Do you handle contents claims?
Yes. Contents disputes often come down to replacement pricing and depreciation. We build a priced inventory with comparable items and age-appropriate depreciation.
My insurer paid part of the claim. Is it too late?
Not necessarily. A partial payment doesn’t usually end your right to dispute the amount, but watch your policy’s deadlines for repairs, depreciation recovery and lawsuits.
Will you visit my home in person?
Yes. An appraisal valuation needs our own inspection and measurements. We cover all three Delaware counties.
Related services
Commercial, Condo & HOA Appraisal
Offices, retail, warehouses, multifamily, churches and associations with large or complex losses.Learn more
Roof & Hail Claim Appraisal
Hail and storm roof disputes: repair versus replace, matching, steep and high charges, and code items.Learn more