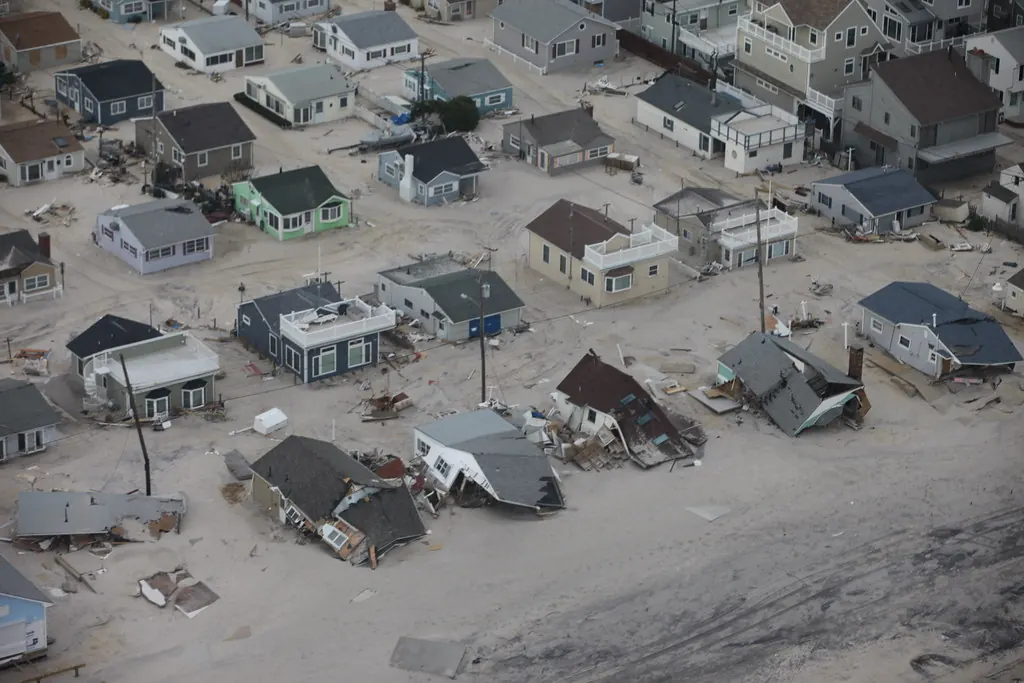
Why commercial claims widen
Commercial property appraisal in Delaware is rarely about one roof. It’s about a whole building system — membrane roofing, rooftop units, curtain wall, interior build-outs — and policy features like coinsurance, ordinance-or-law limits and business income. Small percentage differences on a large scope become large dollar differences.
What we value
- Low-slope roofing: TPO, EPDM, modified bitumen and built-up systems, including tear-off, insulation, tapered crickets and code upgrades.
- Metal buildings: standing-seam and through-fastened panels on warehouses and agricultural structures in Kent and Sussex counties.
- Building envelope: storefront glass, EIFS and masonry, sealants and flashing.
- Interiors: tenant spaces, common areas, elevators, life-safety systems.
- Project overhead: general conditions, supervision, phasing around occupied units, equipment, permits and contractor overhead and profit.
Condominium and HOA claims
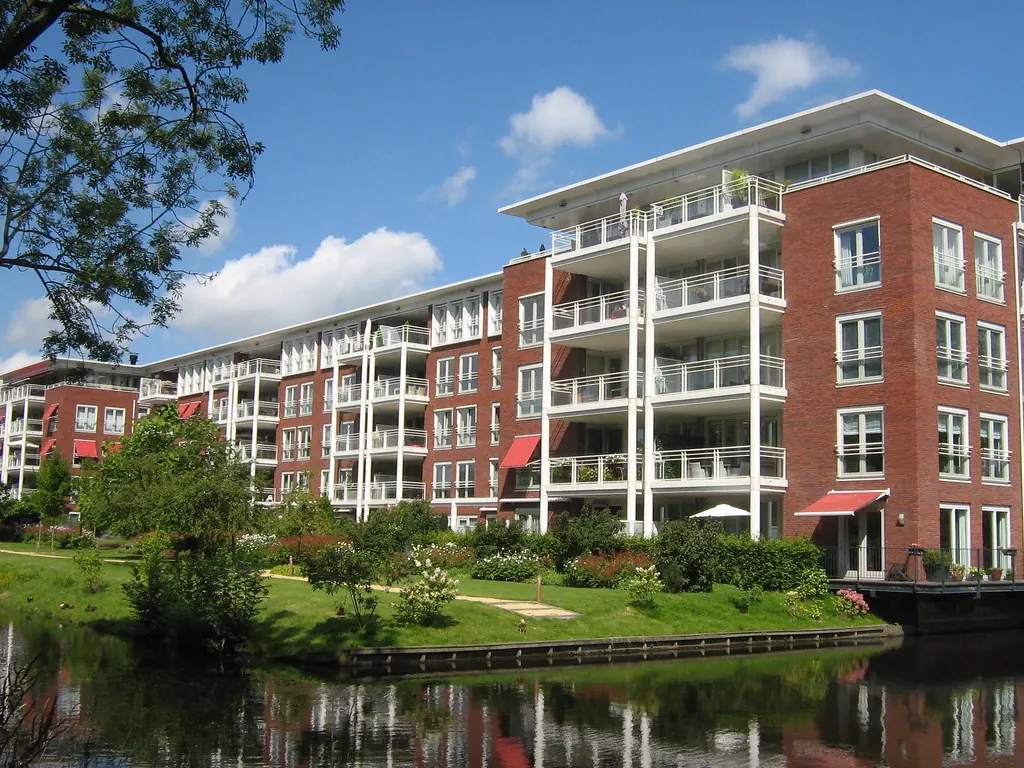
Delaware associations — high-rises on the Wilmington Riverfront, garden-style communities in Newark and Bear, and ocean-block condos in Rehoboth and Bethany Beach — face a coverage split between the master policy and owners’ individual policies. Before we price anything, we read the declaration to confirm who insures what. Boards then get a valuation they can explain to owners and a defined process for resolving the dispute.
Working with your team
We work alongside property managers, engineers, contractors and attorneys. When a structural engineer or roof consultant is needed, we coordinate their findings into the estimate rather than duplicating them. Every report is built to make sense to a board treasurer and to an umpire.
Frequently asked questions
Do you handle business income disputes?
We value the physical loss. For business income we can coordinate with a forensic accountant, since that calculation turns on financial records rather than construction costs.
Can an HOA board invoke appraisal?
If the association is the named insured on the master policy and the policy contains an appraisal clause, the board can usually demand appraisal on the amount of loss. Check your governing documents for any vote requirements.
Do you work on churches and nonprofits?
Yes. Churches, schools and nonprofit buildings often have unique materials, such as slate, stained glass or masonry, that need careful pricing.
Related services
Roof & Hail Claim Appraisal
Hail and storm roof disputes: repair versus replace, matching, steep and high charges, and code items.Learn more
Wind & Tornado Damage Appraisal
Derechos, squall lines and tornadoes: lifted shingles, siding, fences and structural damage.Learn more