Tropical storms in the First State
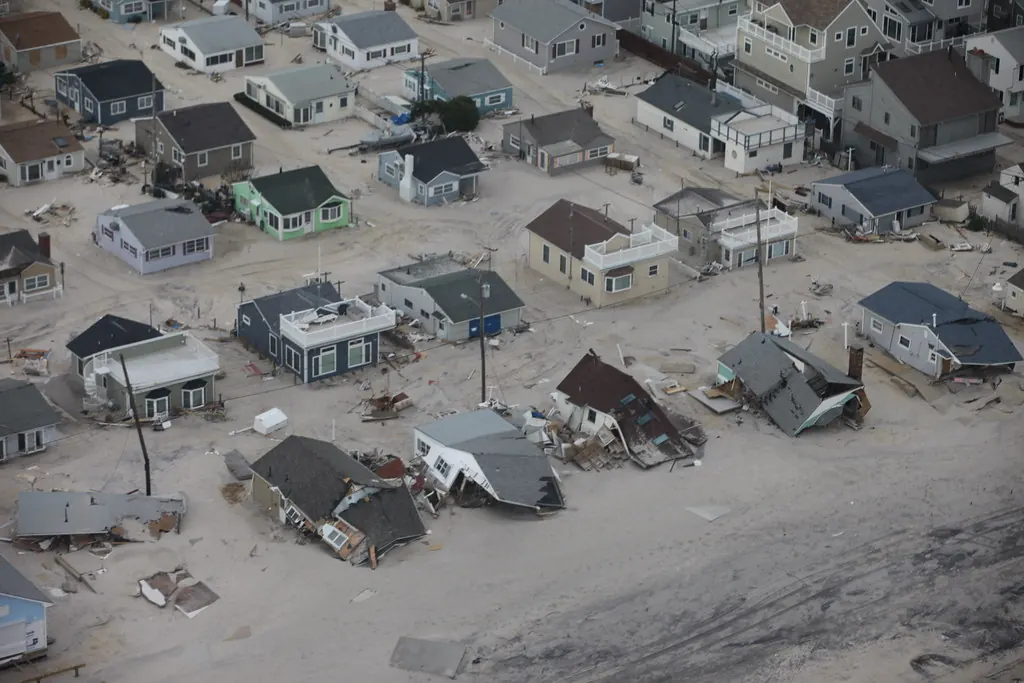
Delaware sits between the Atlantic and the Delaware Bay, with inland bays — Rehoboth, Indian River and Little Assawoman — reaching deep into Sussex County. Tropical systems that track up the coast bring wind, wind-driven rain and surge. Superstorm Sandy in 2012 flooded low areas along the bay and the inland bays and damaged dunes and beachfront property; the remnants of Ida in 2021 sent the Brandywine to record levels in Wilmington. A hurricane claim appraisal in Delaware has to account for all of that.
Wind versus water
Most homeowners policies cover wind and wind-driven rain that enters through a storm-created opening, but exclude flood — rising water from surge, tides or overflowing creeks. Flood is covered separately, typically through the National Flood Insurance Program or a private flood policy. When a coastal home has both kinds of damage, each carrier may point at the other.
- We document the interior water line and debris line separately from wind-created openings.
- We separate roof, window and siding damage from surge-related damage room by room.
- We price each category so both policies can be measured fairly.
Our wind vs. flood split estimator shows how different allocations change what each policy pays.
Hurricane deductibles
Many coastal Delaware policies carry a hurricane or named-storm deductible, often a percentage of Coverage A. On a $600,000 beach house, a 5% deductible is $30,000 — so how the deductible is triggered, and what counts against it, matter a great deal.
Elevated and beach construction
Raised homes on pilings, breakaway walls, decks, outdoor showers and corrosion-resistant fasteners all carry costs a generic estimate may not reflect. We price coastal construction as it’s actually built in Lewes, Rehoboth, Bethany and Fenwick.
Frequently asked questions
Does appraisal work on flood claims?
Appraisal is generally a homeowners or commercial property policy tool. NFIP flood policies have their own dispute process, so we review which policy and which process apply before recommending anything.
The carrier says all my damage was flood. What now?
That is often a mix of coverage and causation questions. We document wind-created openings and wind damage separately so you can see what the homeowners policy should address. A Delaware attorney may be needed if coverage is denied.
How soon after a hurricane should I document damage?
As soon as it’s safe. Photograph everything before cleanup, keep damaged samples if you can, and make temporary repairs to prevent more damage.
Related services
Water Damage Claim Appraisal
Burst pipes, appliance leaks and storm intrusion: drying, tear-out, matching and mold.Learn more
Fire & Smoke Claim Appraisal
Structure, smoke, soot and contents claims, from kitchen fires to total losses.Learn more