Wilmington at a glance
- County
- New Castle County
- Neighborhoods
- Trolley Square, Little Italy, the Highlands, Wawaset Park, Forty Acres, Browntown, Riverfront and Cool Spring
- Housing mix
- Rowhomes, twins, stone and brick single-family homes, Riverfront condos and office towers
Local claim risks
- Creek & river flooding
- Wind-driven rain
- Frozen pipes
- Tree damage
- Fire in attached homes
Claims in a city of attached homes
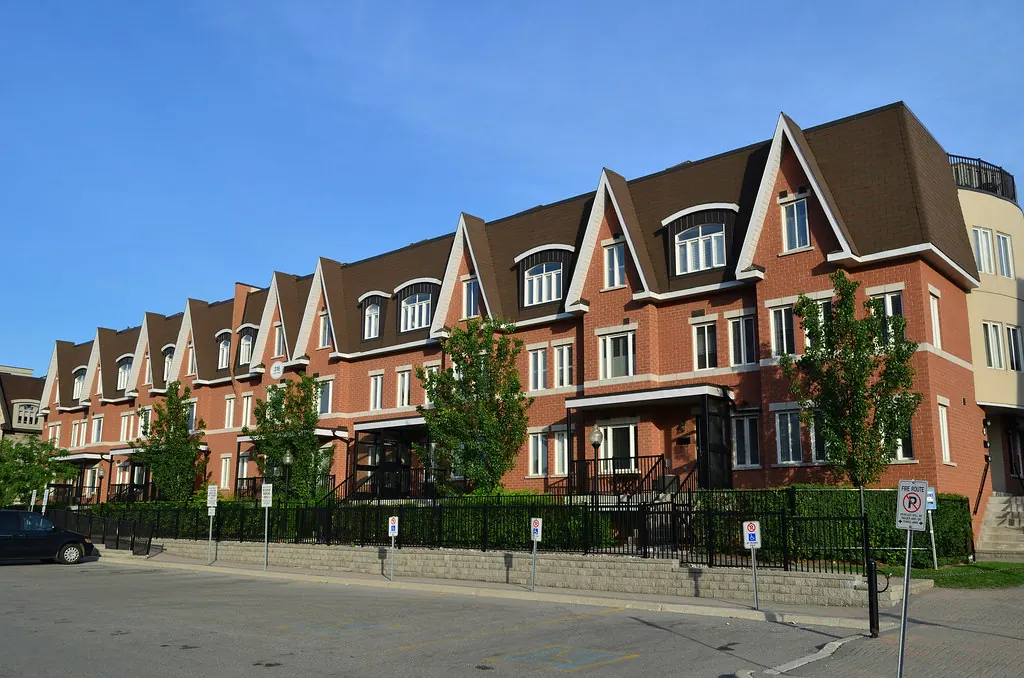
Much of Wilmington is built shoulder to shoulder. In Trolley Square, Little Italy, Browntown and Cool Spring, a fire, roof leak or burst pipe in one rowhome can travel into the next. Party walls, shared roofs and continuous cornices complicate who pays for what, and an estimate that treats a rowhome like a detached house usually misses the extra protection, access and matching work involved.
The Brandywine and the Christina
When the remnants of Ida stalled over the region in September 2021, the Brandywine rose to record levels and flooded neighborhoods and businesses along its banks in Wilmington. River flooding is generally a flood-policy matter, but the same storms bring wind and wind-driven rain into homes that never saw rising water. We help owners separate the two so each policy is measured fairly.
Older housing, specialty materials
Homes in the Highlands, Wawaset Park and along Kentmere Parkway often have plaster walls, slate roofs, copper flashing and detailed millwork. Riverfront condos raise a different set of issues: master policy versus HO-6 coverage, and building systems shared by hundreds of owners. Insurance appraisal in Wilmington has to price both well.
What we see most
- Interior water losses from aging plumbing and winter freeze-ups
- Slate, flat and rubber roof leaks on older homes
- Fire and smoke spreading between attached homes
- Tree damage along the city’s parks and parkways
- Condo association disputes on the Riverfront
Services available in Wilmington
Every Delaware Insurance Appraiser service is available to property owners in Wilmington and the surrounding area:
- Appraisal Clause Representation
- Homeowners Claim Appraisal
- Commercial, Condo & HOA Appraisal
- Roof & Hail Claim Appraisal
- Wind & Tornado Damage Appraisal
- Hurricane & Coastal Storm Appraisal
- Water Damage Claim Appraisal
- Fire & Smoke Claim Appraisal
- Nor’easter & Winter Storm Appraisal
- Carrier Estimate Review
- Umpire & Neutral Appraiser Services
Questions from Wilmington property owners
My rowhome was damaged by a fire next door. Whose policy pays?
Usually your own policy covers damage to your home, and your insurer may then pursue the neighbor’s carrier. We value the damage to your property either way.
Do you handle Riverfront condo claims?
Yes. We review the condominium declaration first to separate the association’s master policy from unit owners’ HO-6 coverage.
Is Ida-related basement water covered?
If the water rose from outside, it is usually a flood-policy matter. Water that entered through storm-damaged roofs or windows may be a homeowners claim.