Why the split matters in Delaware
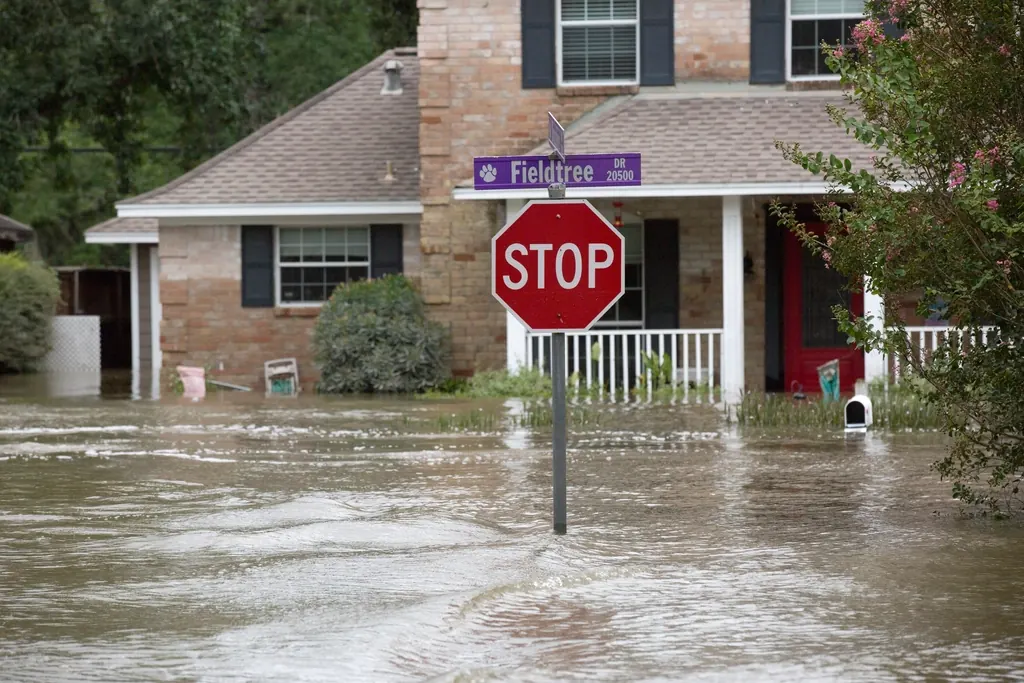
Coastal storms along the Delaware Bay, the Atlantic and the inland bays often bring wind damage and flood damage at the same time. Homeowners policies generally cover wind and wind-driven rain through storm-created openings and exclude flood. Flood policies cover rising water but have their own limits and deductibles. When each insurer argues the other should pay, the allocation decides your recovery.
How the estimator calculates
- The wind share of the total damage goes to the homeowners policy, minus the hurricane deductible (percentage of Coverage A) or a flat deductible.
- The rest goes to the flood policy, minus its deductible and capped at its building limit.
- Anything not paid by either policy is shown as your share.
Try different splits
Move the slider and watch the payments shift. With a large hurricane deductible, a wind-heavy split may still leave you paying a lot; with no flood policy, every dollar allocated to flood is yours. That’s why documenting water lines and wind-created openings carefully is so important. All figures are illustrative.
Questions about this worksheet
Can appraisal decide the wind vs. flood split?
Sometimes appraisers value damage by cause, but whether an appraisal panel can decide causation depends on the policy and the law. Coverage disputes may need an attorney.
Do NFIP flood policies cover contents?
Only if you bought contents coverage. This tool looks at building damage only.
Why does my homeowners policy pay nothing at some splits?
If the wind portion is smaller than the hurricane deductible, the homeowners policy has nothing to pay.
More free worksheets
 Estimator
Claim Gap & Fee Estimator
See the disputed amount, a projected award and what you keep after appraiser and umpire fees.Open worksheet Calculator
RCV / ACV Holdback Calculator
Work out depreciation line by line, your first payment and the holdback you can recover after repairs.Open worksheet Calculator