The Delaware Appraisal Clause in Plain English
A sentence-by-sentence walk through the appraisal paragraph found in most Delaware homeowners and commercial policies.
Journal · 5 min read · September 30, 2026
Appraisal is powerful, but it’s not always the right tool. Here are the situations where we’d steer you elsewhere.
We’re appraisers, but we don’t recommend appraisal for every claim. Here’s when another path is usually better.
Appraisal sets the amount of a covered loss. If coverage is denied, talk to a Delaware attorney.
If the difference is a few thousand dollars, appraiser and umpire fees may consume most of it. A well-documented supplement is often faster.
If a suit limitation or other deadline is near, an attorney should advise you first.
Appraisal locks in an amount. If your photos, estimate and records are thin, build them first. Our readiness check helps.
If you want someone to manage the entire claim from the start, a licensed public adjuster may be a better fit.
We’ll tell you honestly which path makes sense on the first call.
A sentence-by-sentence walk through the appraisal paragraph found in most Delaware homeowners and commercial policies.
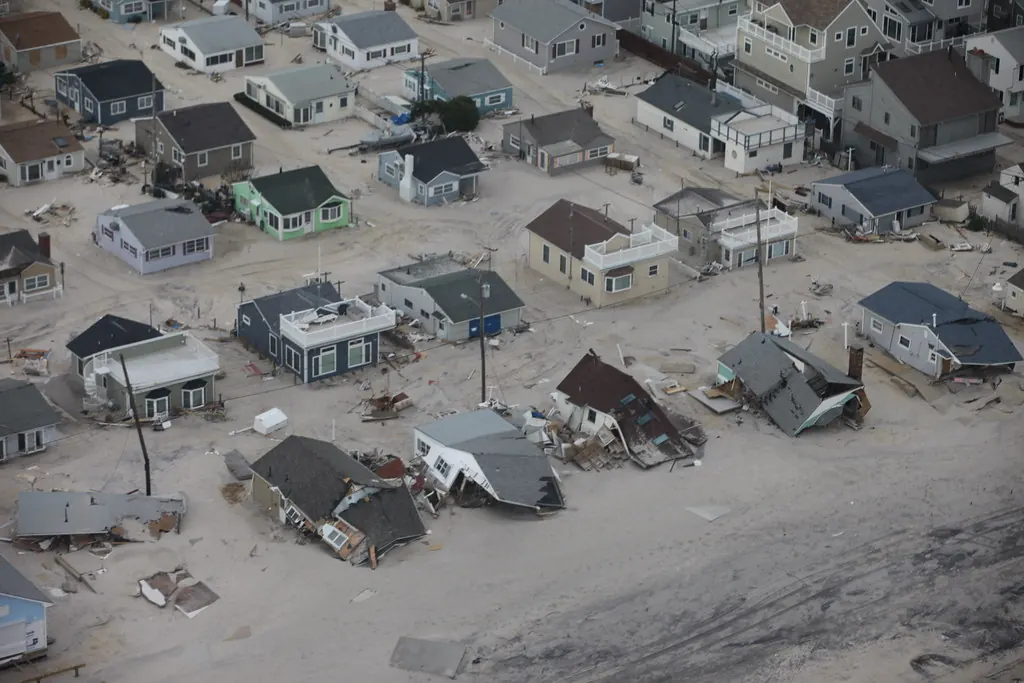
Homeowners policies cover wind; flood policies cover rising water. Here’s how to document both after a storm at the bay or the beach.
Each professional solves a different problem. Picking the right one first saves time and fees.
Send us the carrier’s estimate and your photos. We’ll tell you plainly what we see.