When Appraisal Is the Wrong Move
Appraisal is powerful, but it’s not always the right tool. Here are the situations where we’d steer you elsewhere.
Journal · 7 min read · October 7, 2026
Insurance estimates are dense, but the structure is predictable. Here’s what to look for on each page.
Most carrier estimates follow the same structure. Once you know it, you can spot the usual omissions.
Shows RCV, depreciation, ACV, deductible and net payment. Check that the deductible is correct and note whether depreciation is recoverable.
Each room or roof area lists line items with a quantity, unit price and total. Check that every damaged room and slope is included and that measurements look reasonable.
Look at the age and life used for each item and whether labor is depreciated. Use our RCV/ACV calculator to check the math.
List every missing or under-priced item with photos and support, and send a supplement request. If the gap remains large, consider appraisal.
Appraisal is powerful, but it’s not always the right tool. Here are the situations where we’d steer you elsewhere.
A sentence-by-sentence walk through the appraisal paragraph found in most Delaware homeowners and commercial policies.
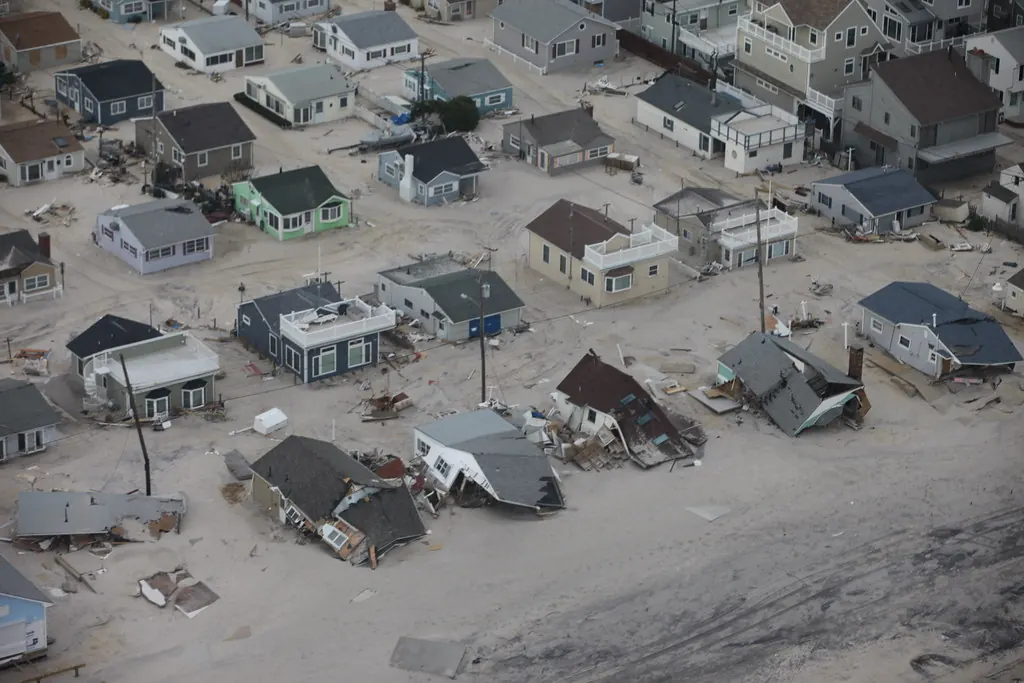
Homeowners policies cover wind; flood policies cover rising water. Here’s how to document both after a storm at the bay or the beach.
Send us the carrier’s estimate and your photos. We’ll tell you plainly what we see.